One Path
You live one path through time, not the average across all of them. Short essays on ergodicity, volatility drag and the Kelly criterion, with the mathematics proved in Lean.
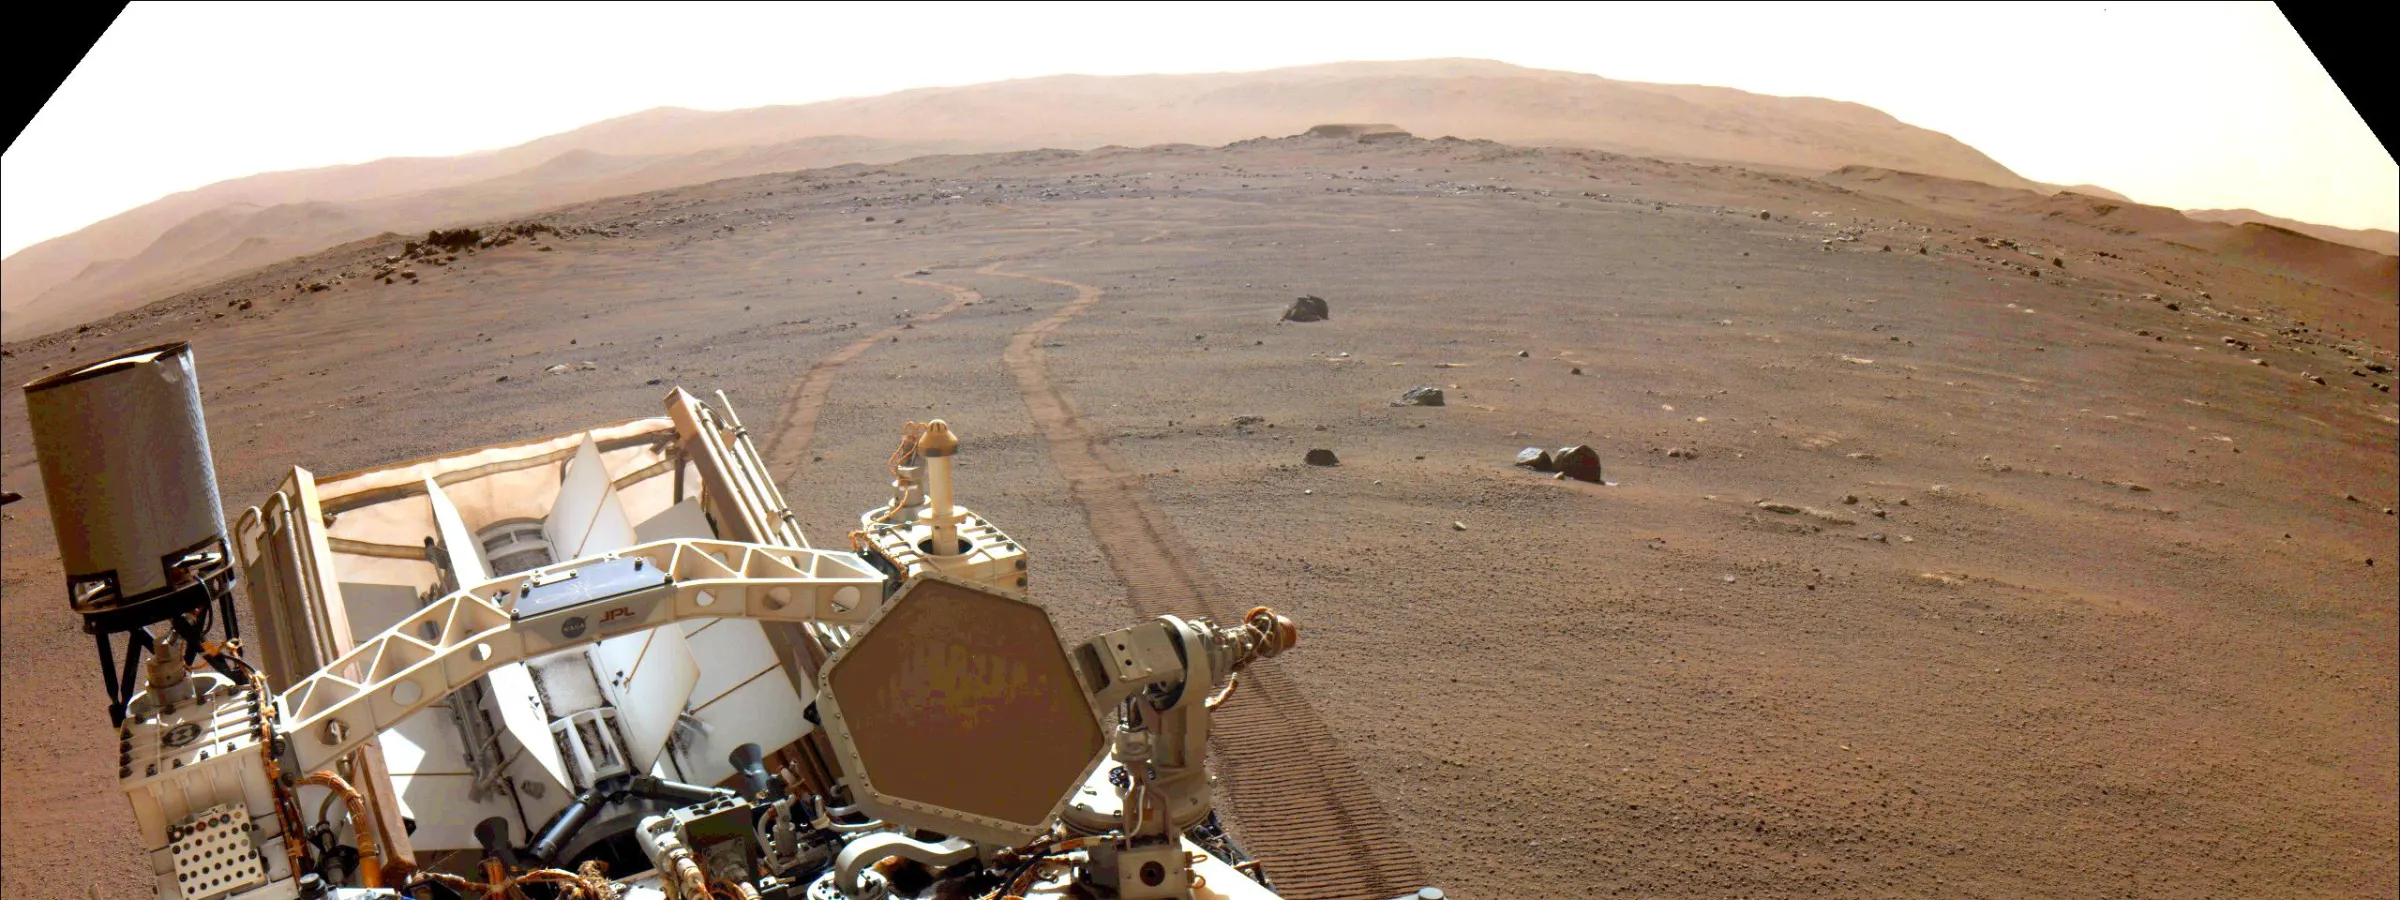
On the image The rover has one history, the tracks behind it. No average over the routes it could have taken tells you where it is now, which is the point of this series. NASA's Perseverance rover looks back at its own wheel tracks in Jezero Crater, Mars, 17 March 2022. Photo: NASA/JPL-Caltech, public domain.
Most of the mistakes I see in how people think about money, risk and companies come from one confusion. The average outcome across many people is treated as if it were the outcome one person should expect. When things add, that works. When things compound, it does not, and almost everything that matters compounds.
These essays explain that idea in short pieces, each with a worked example and a simulation you can play with:
- Ergodicity, explained. Why the average player of a coin game gets rich while almost every player goes broke.
- Volatility drag. Why your average return overstates your wealth, and by roughly how much, checked against forty currencies.
- The Kelly criterion. How much to bet when you have an edge, and why betting twice Kelly earns nothing.
- Insurance. Why a contract that one side loses on average can make both sides grow faster.
The mathematics behind them is proved in Lean 4, in lean-ergodicity: Jensen’s inequality for the logarithm, the time average along one trajectory, volatility drag with an explicit error bound, and the Kelly criterion.
The long versions live in Leptokurtic, especially Finance Is Geometry.
Episodes
-
Episode 1: Why Insurance Makes Both Sides Richer
In expected wealth, insurance is zero-sum: the buyer pays more than the expected loss and the insurer pockets the difference. In the growth rate each side lives through, there is a range of fees where both come out ahead.
-
Episode 2: The Kelly Criterion: How Much to Bet When You Have an Edge
The Kelly criterion says how much of your wealth to put on a bet you expect to win: the fraction that maximizes the growth rate you live through over time. Why overbetting is worse than underbetting, and what it means for investors.
-
Episode 3: Volatility Drag: Why Your Average Return Overstates Your Wealth
Volatility drag is the gap between an investment’s average return and the rate it actually compounds at: roughly half the variance. Where it comes from and what to do about it.
-
Episode 4: Ergodicity, Explained: Why the Average Outcome Is Not Your Outcome
A process is ergodic when the average over time equals the average across people. Wealth is not ergodic, and that changes how you should bet, invest and size risk.
This series is in progress. More episodes are coming.