Why Insurance Makes Both Sides Richer
In expected wealth, insurance is zero-sum: the buyer pays more than the expected loss and the insurer pockets the difference. In the growth rate each side lives through, there is a range of fees where both come out ahead.
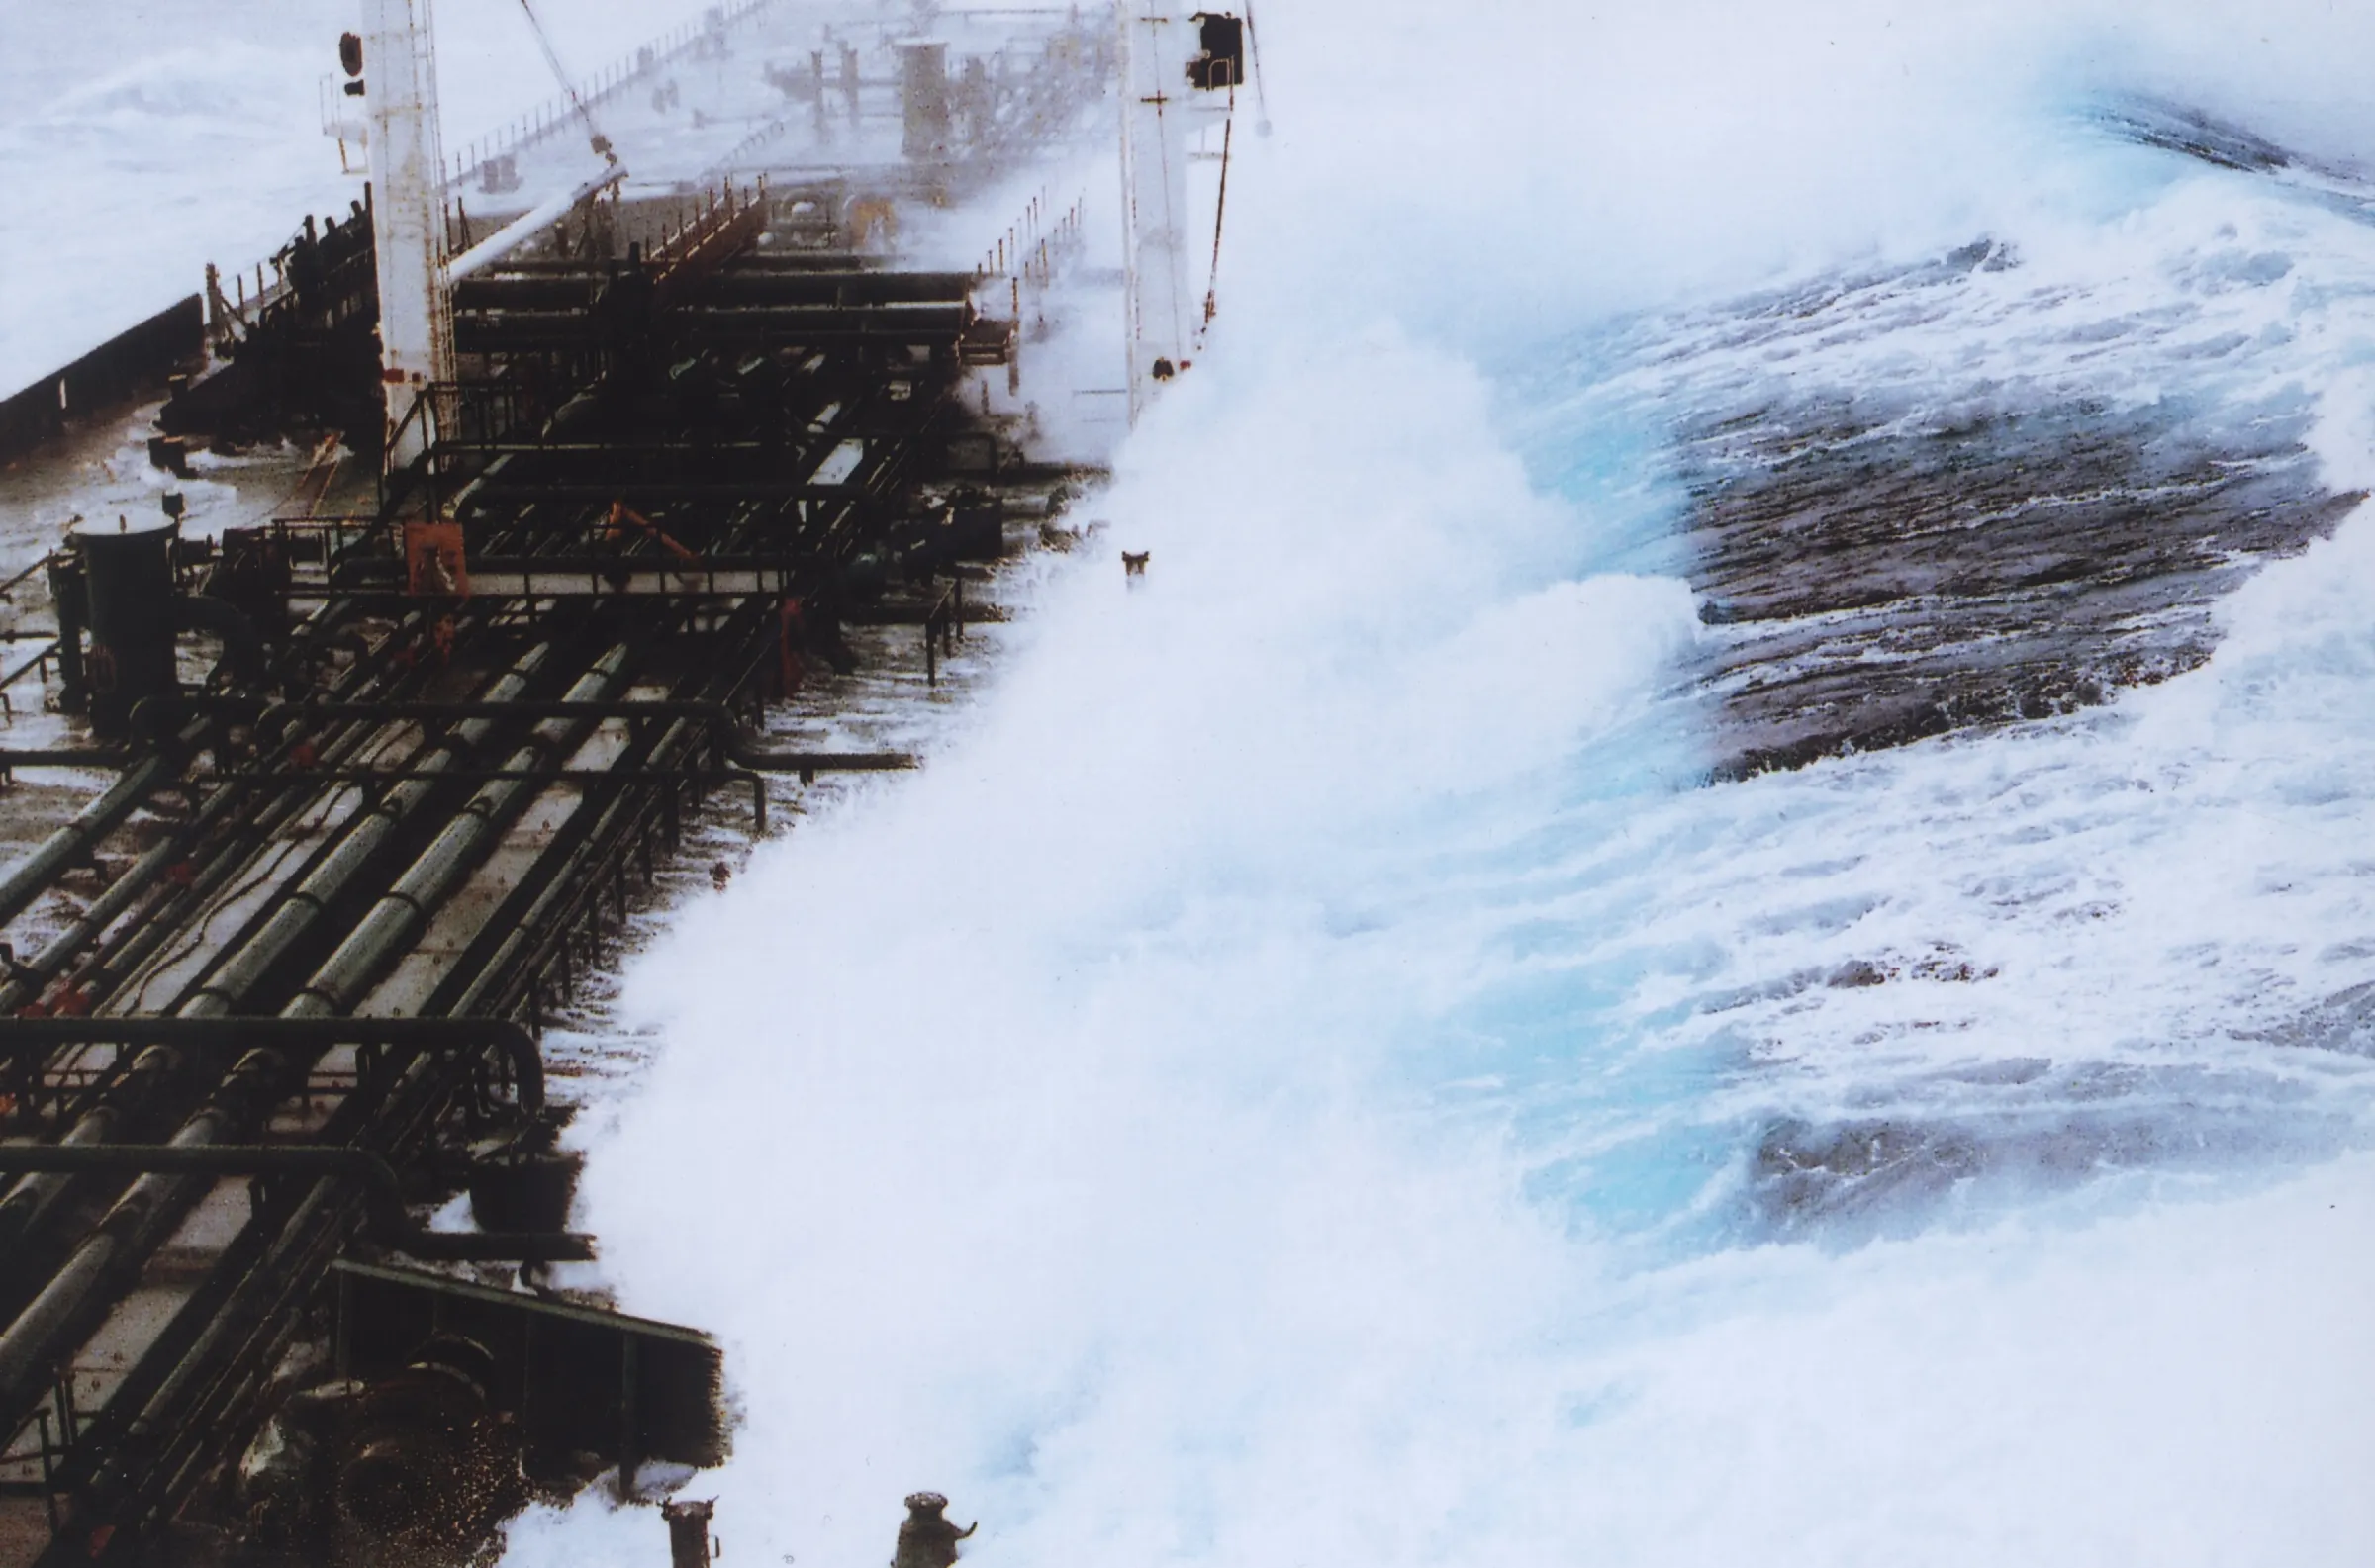
On the image One wave in a whole voyage does the damage. For the ship's owner it can be ruin; spread across an insurer's books it is one claim among many, and that difference in scale is what makes insurance worth buying and selling. A wave estimated at more than 60 feet breaks over the deck of an oil tanker heading south from Valdez, Alaska, February 1993. Photo: Captain Roger Wilson, NOAA Photo Library, public domain.
Measured in expected wealth, insurance is zero-sum. The buyer pays a fee larger than the expected loss, the insurer keeps the difference, and whatever one side gains on average the other loses. Measured in the growth rate each side actually lives through over time, it is not. There is a range of fees at which both the buyer and the insurer grow faster than they would without the contract.
This is the fourth piece in a series. It uses the idea from the first, that the average across possible outcomes is not the outcome you live, and the cost from the second, that volatility drags down compound growth. The argument is from Ole Peters and Alexander Adamou’s paper “Insurance makes wealth grow faster.”
#The puzzle
If insurance only made sense in expected wealth, it would be hard to explain why anyone buys it. Insurers are profitable, so on average policyholders pay more than they get back. The textbook answer is risk aversion: people dislike uncertainty, so they pay to remove it. That explains the buyer by giving them a particular taste. It does not explain why a contract that one side loses on average is so common, or why insurers, who also face risk, are happy to take it on.
#A shipowner and an insurer
Here is the smallest version of the argument. A shipowner has 200,000 dollars and is about to send cargo on a voyage. With probability one half the cargo is lost, and the owner loses 100,000. An insurer with 1,000,000 offers to cover the loss for a fee.
Start with expected wealth. Uninsured, the owner ends with 200,000 or 100,000, an expected 150,000. The expected loss is 50,000, so any fee above 50,000 makes the owner poorer on average and the insurer richer by exactly the same amount. In expected wealth, the contract can only help one side.
Now look at what each side compounds at. The number that matters for repeated voyages is the average of the logarithm of wealth, or equivalently the geometric average of the outcomes. Uninsured, the owner’s geometric average is $\sqrt{200{,}000 \times 100{,}000} \approx 141{,}421$ dollars. Insured at a fee of 55,000, the owner ends with 145,000 for sure. That is higher, even though the owner paid 5,000 more than the expected loss.
The insurer, at the same fee, ends with 1,055,000 or 955,000. Its geometric average is $\sqrt{1{,}055{,}000 \times 955{,}000} \approx 1{,}003{,}755$, above the 1,000,000 it started with. Both sides grow faster.
#The range of fees
At a fee of 55,000 both gain, but the deal works over a range. The owner gains from any fee below $200{,}000 - \sqrt{2} \times 100{,}000 \approx 58{,}579$. The insurer gains from any fee above about 51,249. Every fee in between makes both sides better off in growth, and every one of them is above the expected loss of 50,000, so the insurer also makes money on average.
The simulation below lets you change the insurer’s wealth. The blue curve is the owner’s change in growth rate, the red curve the insurer’s, and the green band the fees where both are positive.
Open this simulation in Explore →
Move the insurer’s wealth up and the band widens toward the expected loss: a very large insurer will take the risk for barely more than 50,000. Move it down and the band shrinks. It survives even when the insurer is exactly as rich as the owner, because the insurer starts with no risk at all, and it only closes when the insurer is poorer than about three quarters of the owner.
#Why both can win
The surplus comes from volatility drag. A loss of 100,000 is half the owner’s wealth, a huge swing, and the drag on growth grows with the square of the swing. The same loss is a tenth of the insurer’s wealth, a small swing with a small drag. Moving the risk from where it is large relative to wealth to where it is small removes most of the drag. That removed drag is real growth, and the fee splits it between the two sides.
Expected wealth cannot see any of this, because it ignores the size of the swing relative to the wealth that has to absorb it. It treats a 100,000 dollar loss the same whether it happens to someone with 200,000 or with 1,000,000. Anyone who has to live through the loss does not.
The same logic explains why pooling works. Peters and Adamou show that people who share their risks, pooling and redistributing their wealth each period, grow faster than any of them would alone, with the drag falling as the pool gets larger. An insurer is a pool with a balance sheet.
#Checked in Lean
The example is proved in lean-ergodicity, in units of 100,000: an owner with 2 who can lose 1, an insurer with 10. Every fee from 0.513 to 0.585 raises the growth rate of both.
theorem insurance_win_win {F : ℝ} (hlo : 513 / 1000 ≤ F) (hhi : F ≤ 585 / 1000) :
    ownerUninsured < ownerInsured F ∧ insurerUninsured < insurerInsured F
The same file proves that in expected wealth the two sides’ changes add up to zero for every fee, so no fee helps both, and gives the exact condition under which each side gains.
#The limits
The example has one voyage, a coin-flip loss, and an insurer that holds a single policy. Real insurers hold many independent policies, which makes the risk they carry smaller still and the case for insurance stronger. Real buyers also misjudge the odds, insurers face correlated catastrophes, and people with insurance may take more risk. None of that changes the central point, which is that a contract one side loses on average can still make both sides grow faster.
Critics of ergodicity economics point out that the same result follows from expected utility with logarithmic utility, so nothing here requires abandoning standard theory. That is true. What the growth framing adds is a reason for the logarithm that comes from how wealth compounds, rather than from an assumption about how people feel about risk.
#Further reading
- Ergodicity, Explained: why the average outcome is not yours.
- Volatility Drag: why swings cost growth, and how much.
- The Kelly Criterion: how much to bet when you do have an edge.
- Ole Peters and Alexander Adamou (2015). “Insurance makes wealth grow faster.” arXiv.
- Ole Peters and Alexander Adamou (2015). “An evolutionary advantage of cooperation.” arXiv.
From the series One Path.
Written with an LLM in the loop, like everything here. The ideas and the mistakes are mine. More on how I write.